“House hacking” — buying a small multifamily, living in one unit and renting the others — got sold on social media as a cheat code to living for free. In 2026 that specific promise is rare. But the honest version is arguably better than the hype: not a free house, but a door into real estate that was otherwise closed, and a housing cost cut to a fraction of normal. Here are the real numbers.
The FHA math that makes it work
The engine is the loan. An FHA loan needs just 3.5% down on a property with up to four units, and lenders will count up to 75% of projected rent from the other units toward your qualifying income — so a duplex or fourplex is reachable on a modest income.
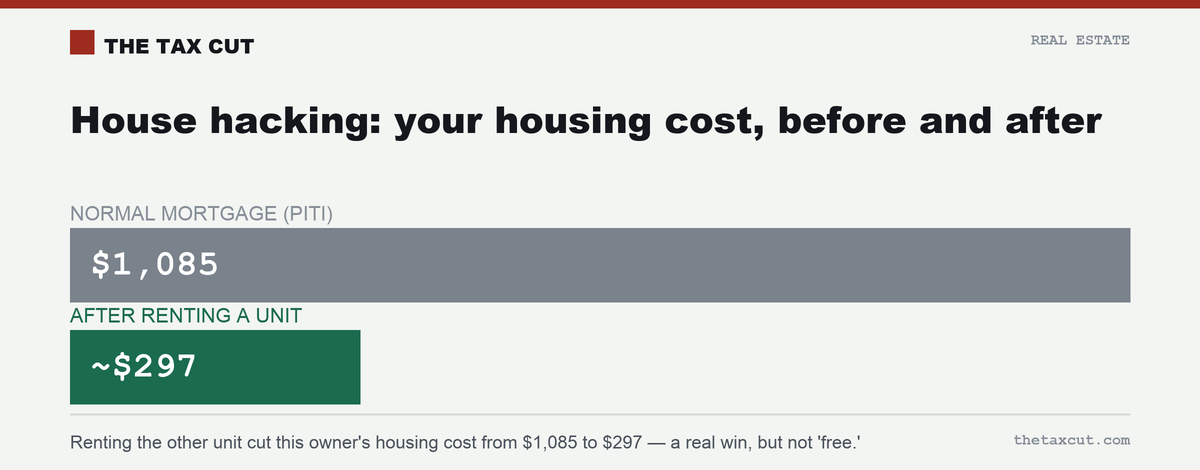
Take a real Midwest example: a $135,000 Cleveland duplex with an all-in FHA payment (PITI) of $1,085/month. Rent the other unit for $875, and your effective housing cost drops to $297. That’s the mechanism — the tenant’s rent pays most of your mortgage.
Source: Mortgage Architects — FHA house hacking rules & limits (2026) · checked 2026-07-29
“Free” is rare — but the range is real
The “live for free” version does happen — usually on a triplex or fourplex where three units’ rent exceeds your PITI. But in most markets, house hacking reduces your housing cost rather than eliminating it.
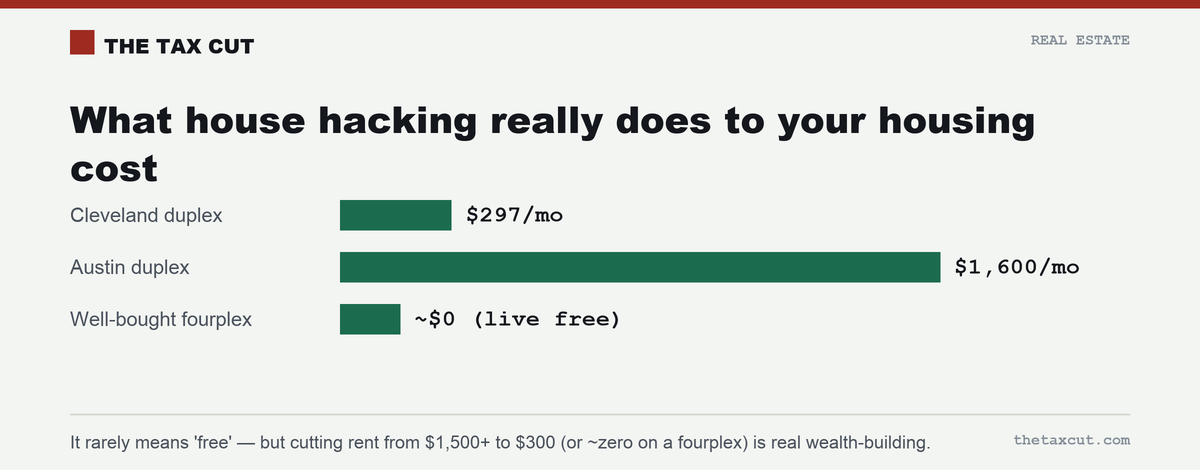
In a pricier market, an Austin $450,000 duplex with a $3,400 PITI, renting the other side for $1,800, still leaves a $1,600 housing cost — a big cut from renting solo, but not free. A well-bought fourplex (live in one, rent three) can genuinely hit ~$0 or better. The number depends entirely on market and rents — but even the “$1,600” case is wealth-building most renters never access.
Source: Ledwell Realty — House hacking 2026: what the hype got wrong · checked 2026-07-29
The costs the “free house” pitch skips
House hacking is still landlording, and the same costs that hit any rental apply here — they just hide behind the low housing number:
- Vacancy. The month a unit sits empty, you cover the whole mortgage. Budget for it.
- Repairs and CapEx. Toilets, roofs, and furnaces don’t care that you live there. The 50% rule still applies to the rented portion.
- You live next to your tenants. Noise, disputes, and 11pm maintenance calls are now literally next door — a real quality-of-life cost.
- Management is you. Screening, leases, rent collection — the job comes with the savings.
So the honest “effective housing cost” is a bit higher than rent-minus-mortgage once you reserve for vacancy and repairs. The $297 is the sticker; budget a cushion and it’s more like $400–$500 — still excellent.
So do the real numbers work?
- It rarely means “free” — but it routinely cuts housing costs from $1,500+ to $300–$600, and can hit $0 on a well-bought fourplex.
- FHA 3.5% down and 75%-of-rent qualifying make it one of the few low-capital ways into real estate.
- It’s real landlording — vacancy, repairs, CapEx, and living next to tenants are the price.
- The true win is the open door, not a free house: you’re building equity and rental income while your housing cost shrinks.
House hacking is one of the genuinely smartest moves in real estate for someone starting out — just not for the “live 100% free” reason it went viral. Judge it by the real effective housing cost after a repair-and-vacancy cushion, and by the equity you’re building — and it’s a rare case where the honest number is still very, very good.
People also ask
Does house hacking really let you live for free?
Rarely in 2026 — that’s mostly a triplex/fourplex outcome. More commonly it cuts your housing cost sharply: one real duplex example dropped a $1,085 mortgage to a $297 effective cost after renting the other unit.
Source: Ledwell Realty — House hacking 2026 · checked 2026-07-29
How much do you need to house hack?
With an FHA loan, just 3.5% down on up to four units, and lenders count up to 75% of projected rent toward qualifying income — making a duplex or fourplex reachable on a modest income.
What are the downsides of house hacking?
It’s real landlording: you cover the full mortgage during vacancies, pay for repairs and CapEx, live next to your tenants, and handle management. Budget a repair-and-vacancy cushion on top of the headline savings.
Is house hacking worth it in 2026?
Yes for most first-time buyers who can tolerate landlording — cutting housing costs from $1,500+ to a few hundred (or zero) while building equity is a rare, high-value move, even if it’s not literally “free.”
See it for your own numbers
Every calculator shows revenue. This one shows what lands.
Related on The Tax Cut
- What does a rental property actually cash flow? — the landlord costs that apply to your rented units too.
- Airbnb arbitrage profit — another low-capital way into real estate, with different risks.
- What is the 50% rule in real estate? — how to budget the repair and vacancy cushion.